


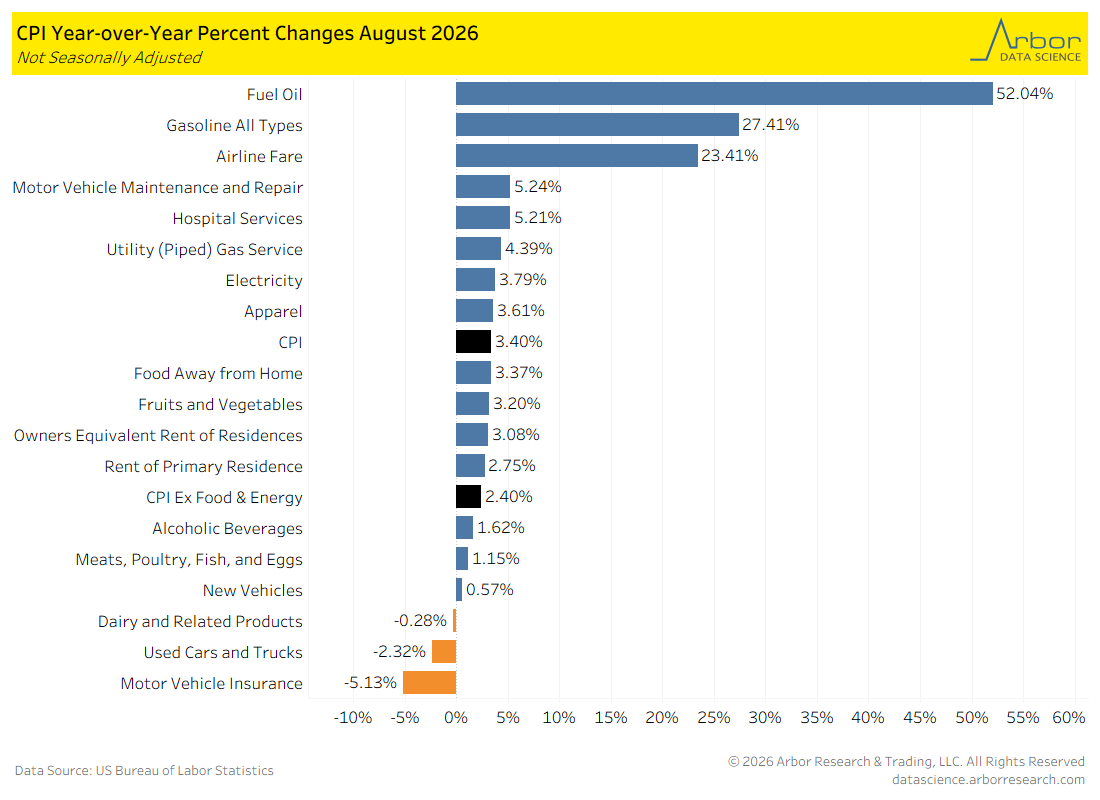
And then CPI decided to be uncooperative… Interestingly, there were a few positives. But housing refusing to decelerate meaningfully is a headscratcher. At these levels of mortgage rates, it should be one of the more disinflationary aspects of the print. But it was not. It should not be a surprise that energy was a problem for this print. It is going to a bigger one for the next one.
With a rate hike now priced in for September 2026, the question is what might affect it in the later part of the year. OER and rent might be the places to look for how efficacious the rate hike (and the threat of rate hikes) might be.
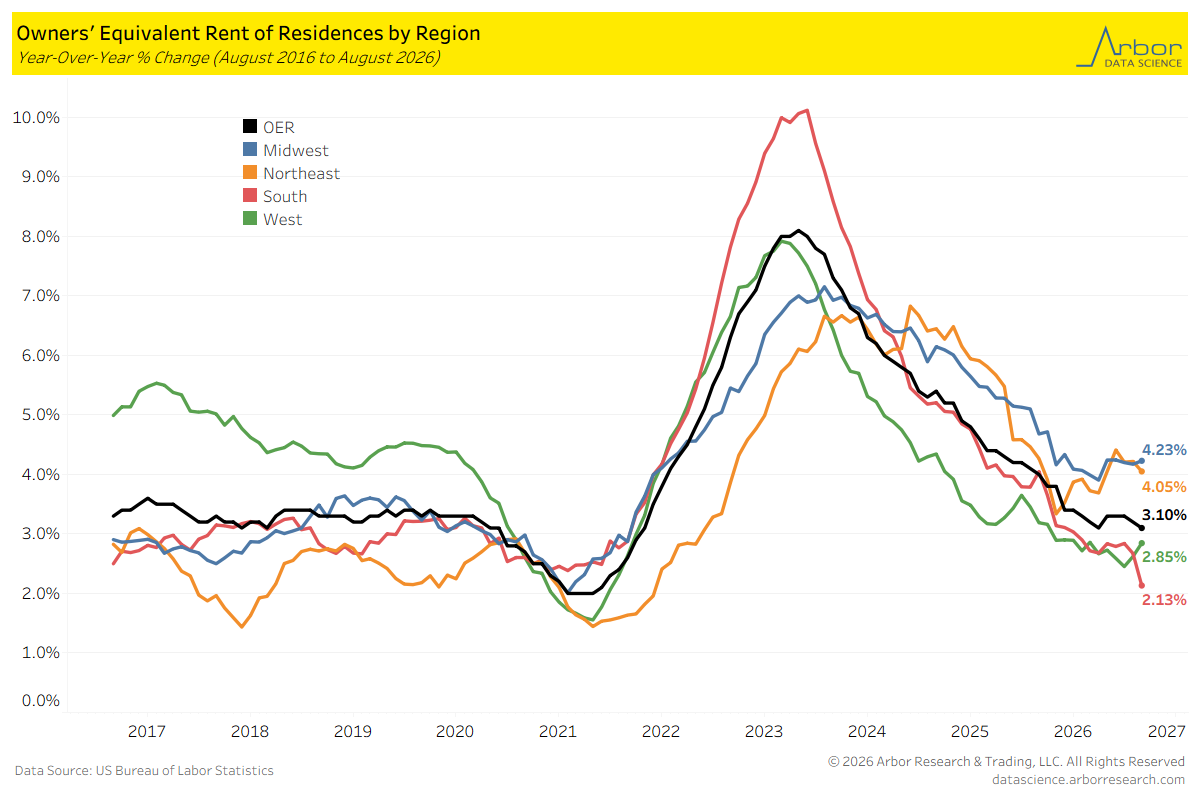
And it gets a bit more complicated for OER when you dig into the data. The South is doing what would be expected in this type of environment. It is falling off a cliff. But the West is not and neither is the Midwest. Those are both accelerating. Meanwhile – somehow – the Northeast is simply unwilling to dis-inflate. This dynamic is somewhat odd. The South is the largest portion of OER (by a wide margin), and its disinflation would normally drag the reading significantly lower. The rest of the country is simply not (yet) participating in it.
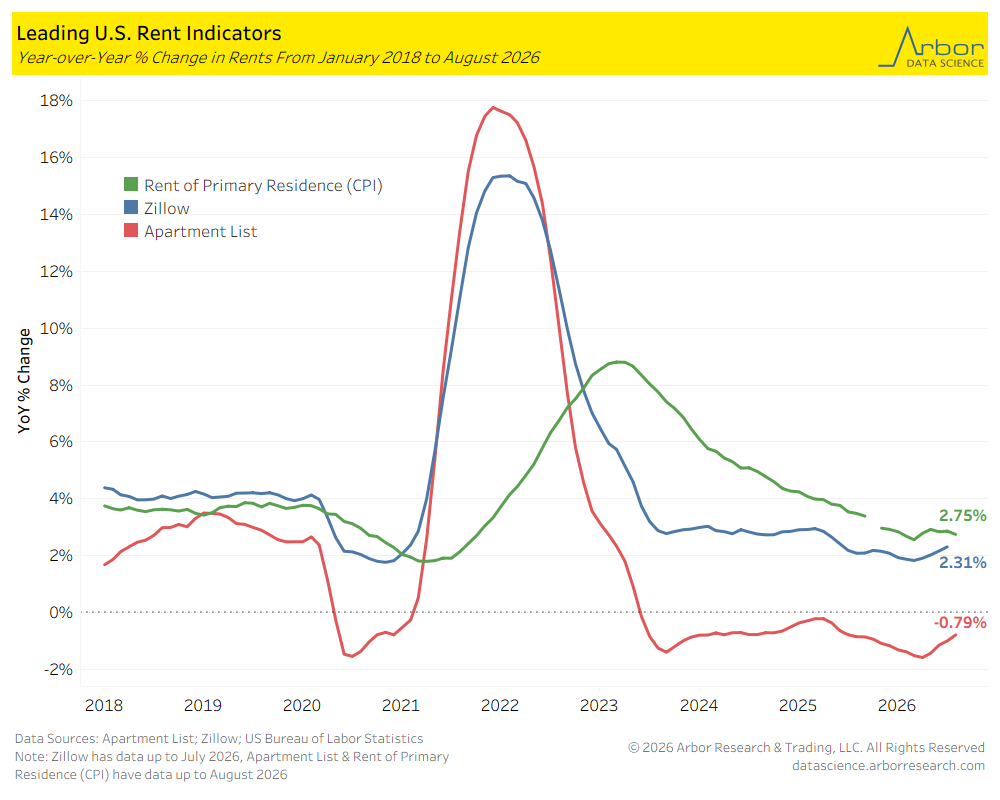
Rent is also a bit of an issue. The CPI figure has now converged to the more real time indicators. And that means that there is little room for the figure to drop. There may be another 30 to 40 basis points of disinflation. But that might be about it for rent. Zillow is showing an acceleration, and that could begin to creep into the official figures in the near to medium term.
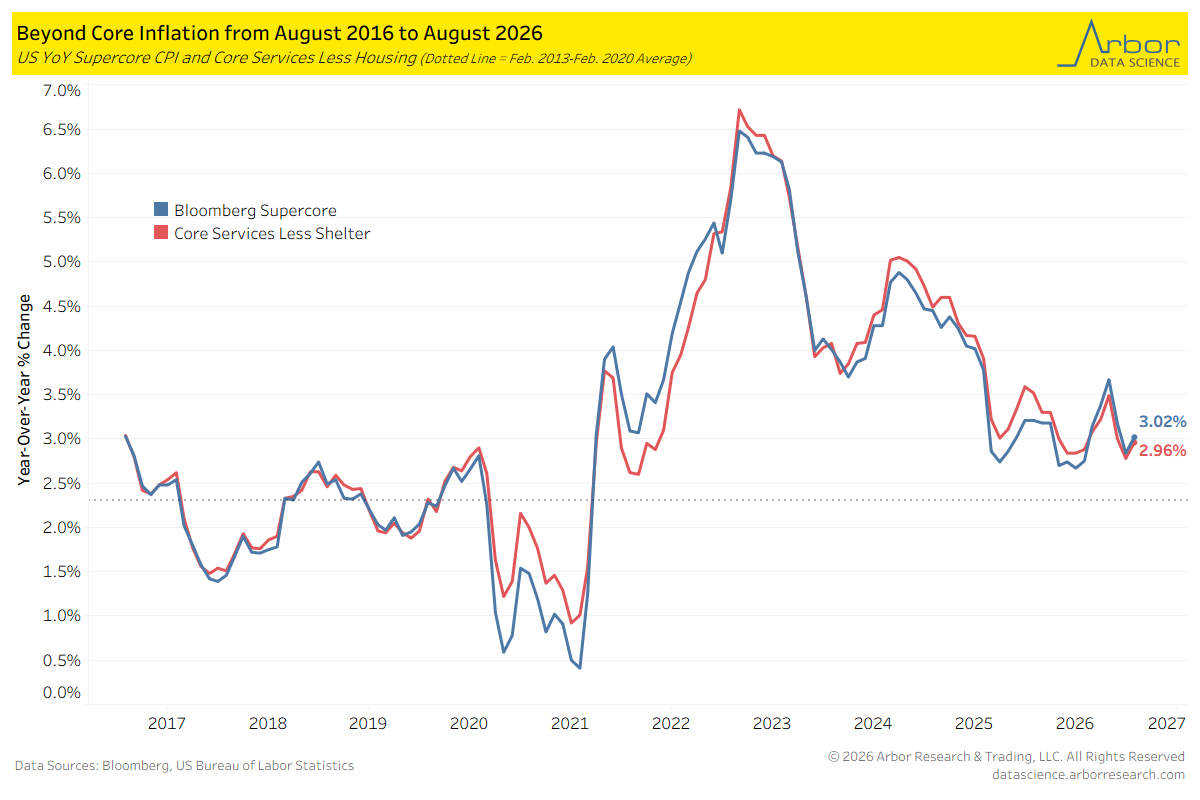
Not even the Supercores are playing along. The disinflation of the past couple of months has stalled. And that is even with components like auto insurance seeing deeply negative prints. That is going to be a problem for the FOMC. The market is not doing the job for it on the inflation front, particularly when you apply it to the sticky services portion of the CPI.
Does a 0.25% hike solve the current issue? It might help. But mortgage rates are already high, and OER is not decelerating in a meaningful way. Will there be anything that reacts meaningfully to a slightly tighter FOMC stance? Maybe. But it is unlikely to be enough to push the headline or core lower in the near-term. In essence, this is not the print the FOMC wanted to see. It points to sticky inflation underlying an energy shock. And neither of those have easy policy solutions.