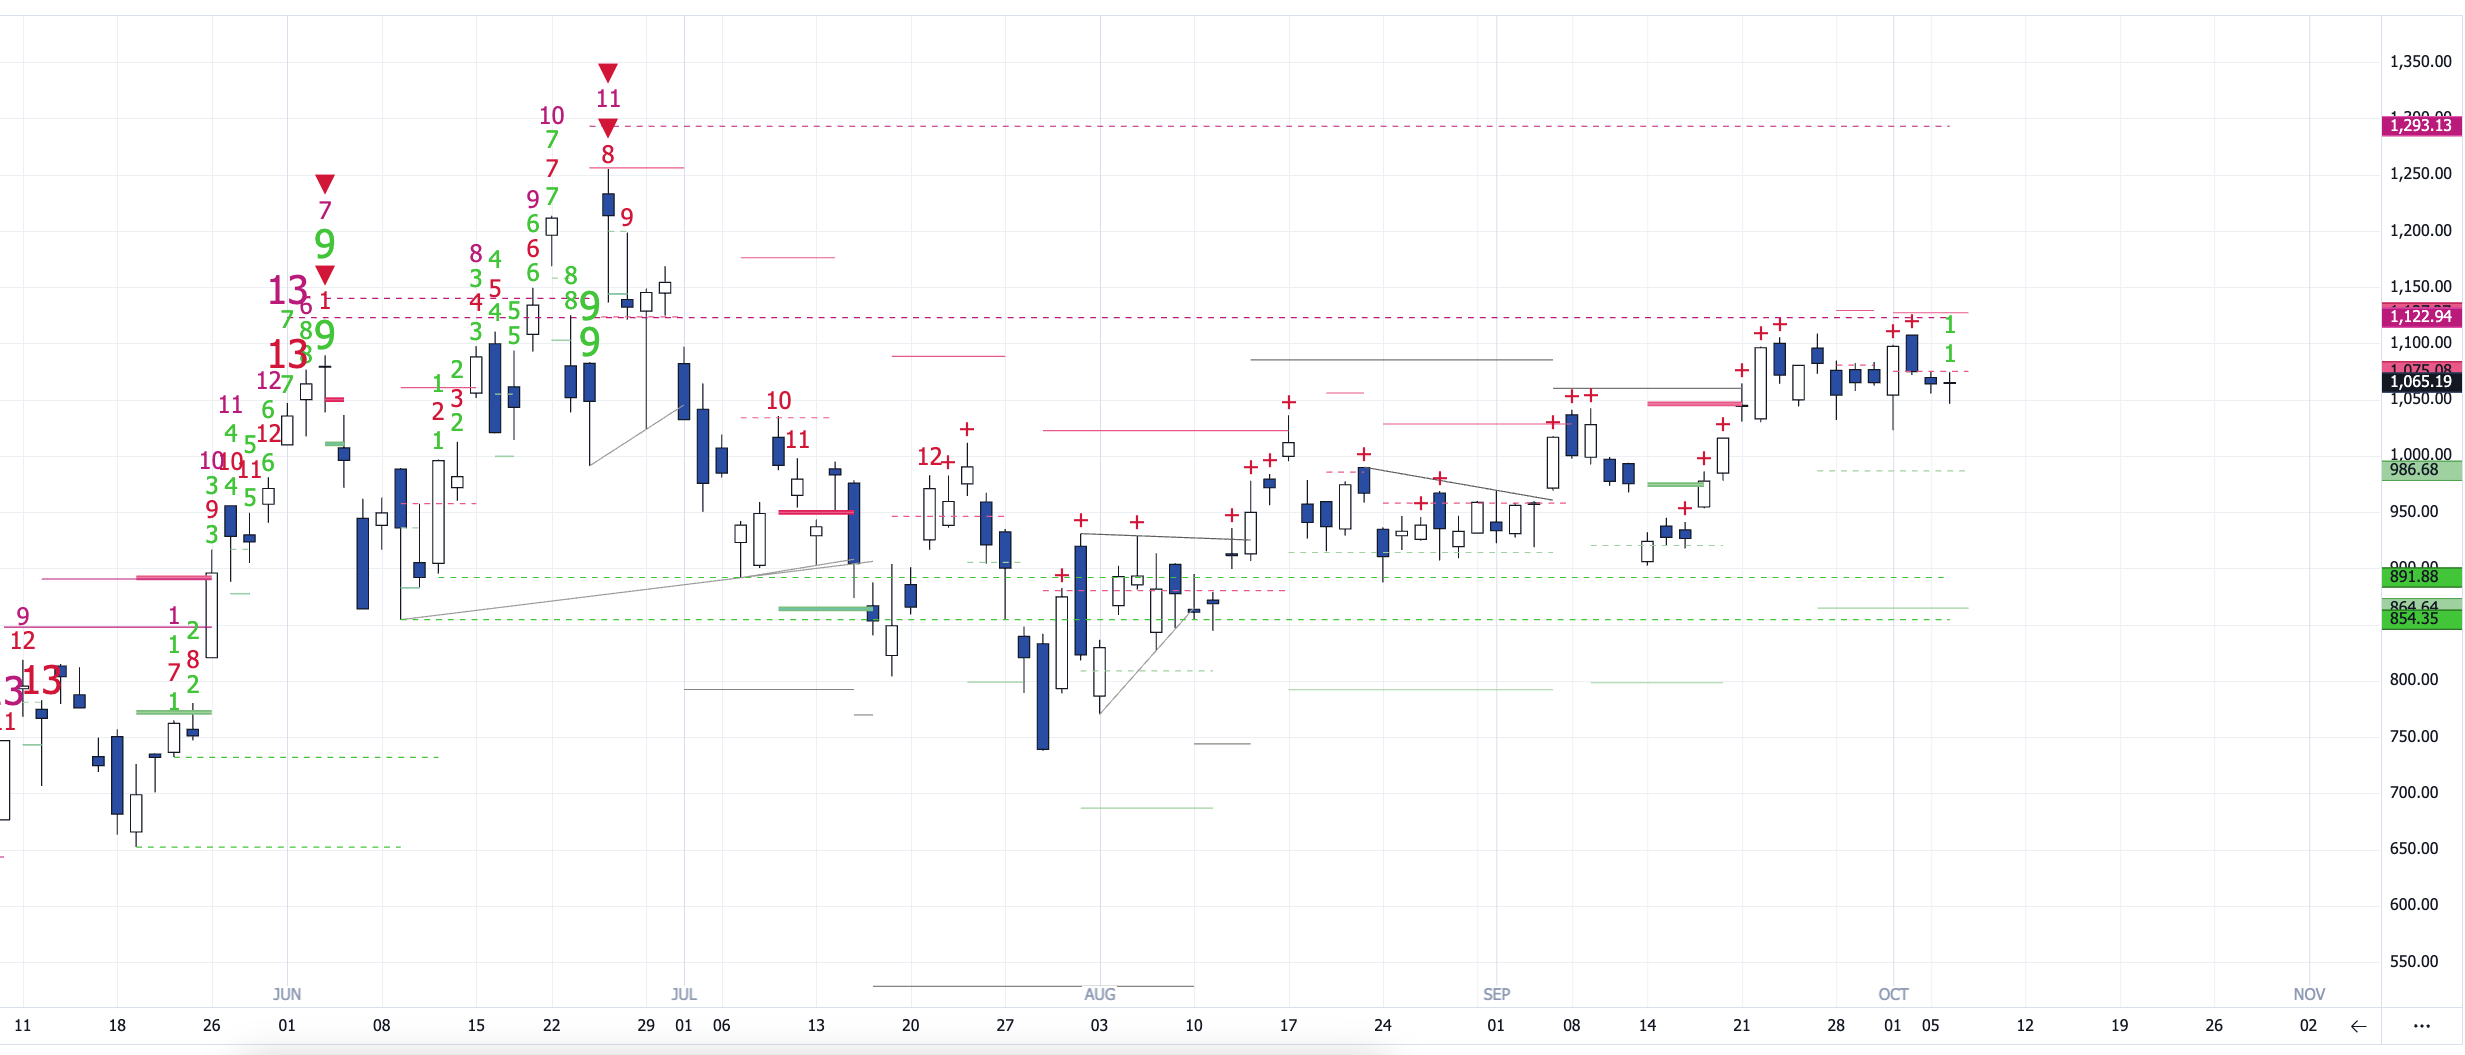
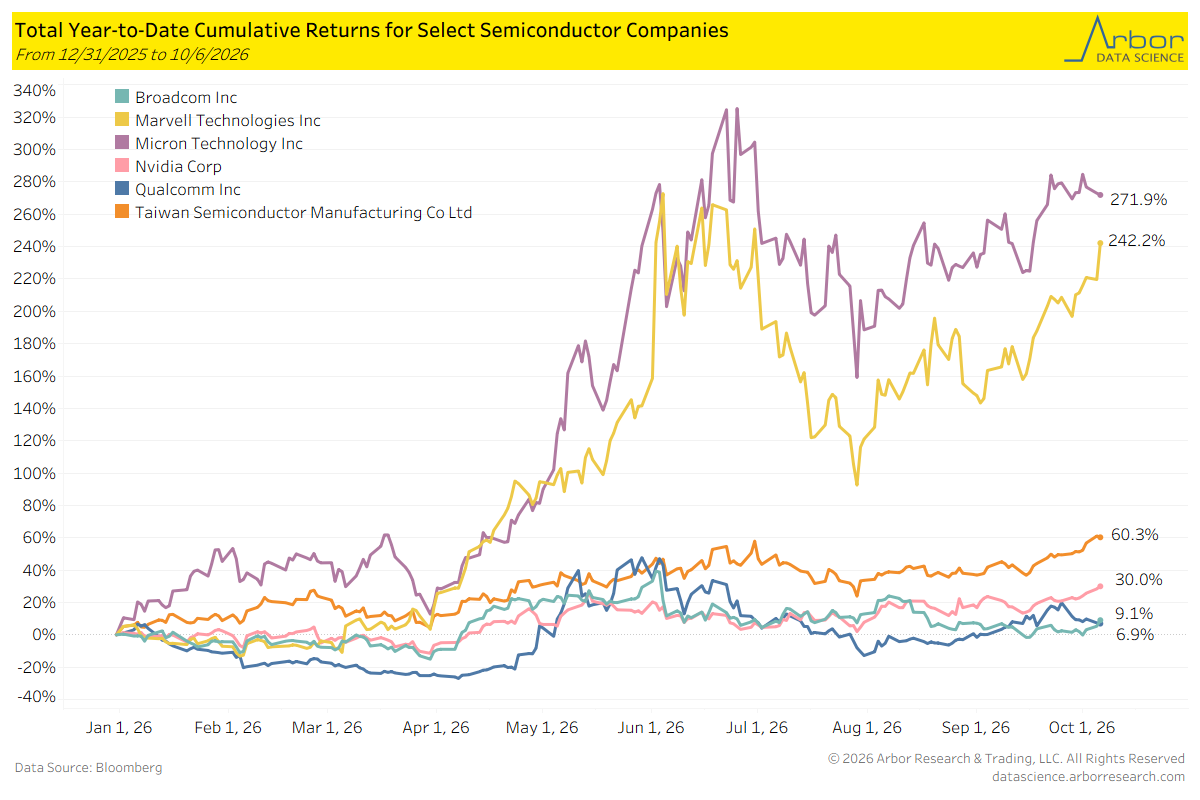
As a follow-up to my July 8, 2026 post, Why Chipmakers Win, While Hyperscalers Spend, Micron reported its FY 2026 results on September 30, 2026. It reported revenue of $133.2 billion, up 256% with an EPS of $75.52. Micron’s stock closed on October 5, 2026 at $1,064, up 273% for the year and 12% below its June 25, 2026 high of $1,214 (after a 39% drawdown that bottomed on July 29, 2026).
Micron reported a record $39.8 billion in quarterly DRAM revenue in 4Q 2026. NAND (non-volatile flash memory chips) revenue was $14.1 billion with prices up about 30%.
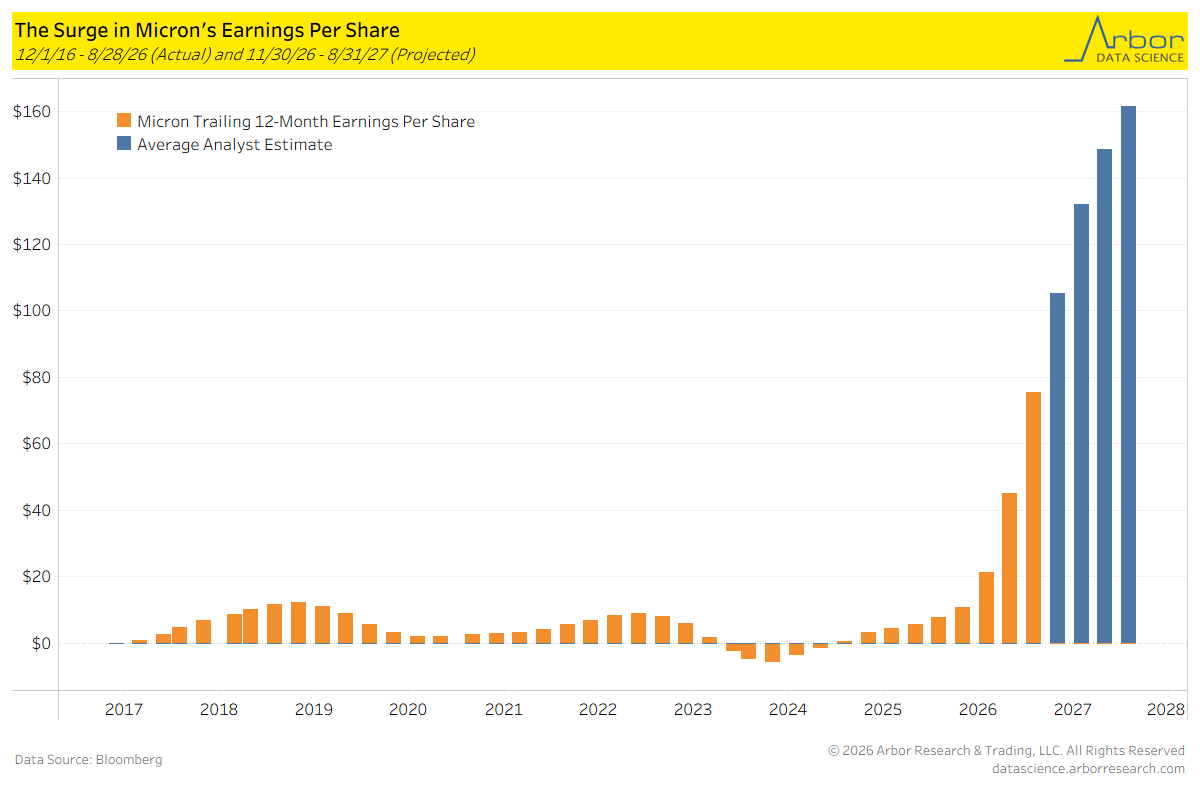
The blue bars in the chart below are the Street’s estimates for Micron’s trailing EPS with projections of: $105 by November 2026, $132 by February 2027, $149 by May 2027 and $161 by August 2027.
Micron announced that it has signed 26 take-or-pay customer agreements covering more than 35% of its revenue through 2030, with some now extended into 2031 (approximately $150 billion of remaining performance obligations and $32 billion of customer financial commitments). It does not have line of sight to when supply and demand return to balance.
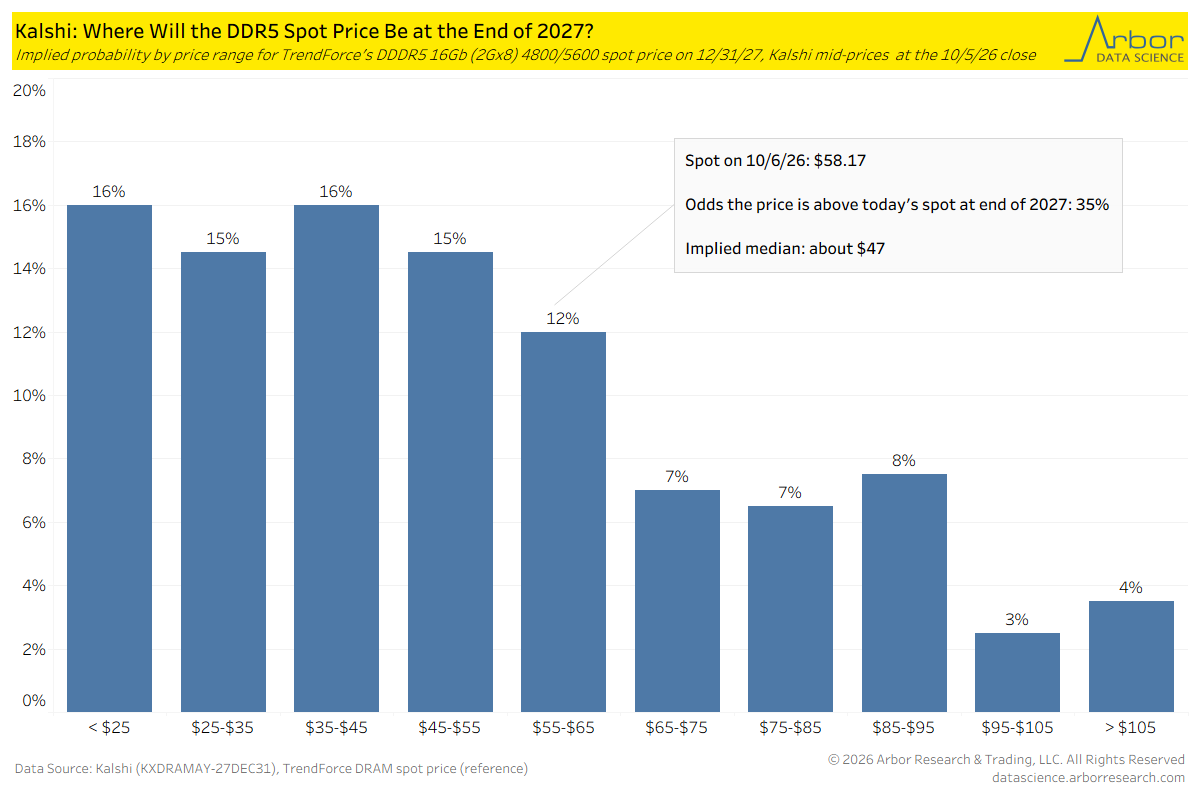
Kalshi has a market on TrendForce’s DDR5 16Gb spot price at the end of 2027, in $10 strikes from $25 to $105. The bars are the probability of each range from the October 5, 2026 mid-prices. The spot price was $58.17 on October 6, 2026 and the market puts 35% on the price being above that at the end of 2027. The implied median is about $47, with a 16% chance of a price below $25. TrendForce’s own forecast for the current quarter is for conventional DRAM contract prices to rise 10% to 15% and NAND 15% to 20%.
On the technical side, I just wanted to do a quick recap of the prior analog that I had posted. It was interesting because the recent decline off the high was one of the biggest ones that Micron ever had. So, charting an analog of the historical path of prior peaks is appropriate. In every other rollover period, we should start to see a pretty significant decline from a correction off the peak on a lower high from here, as per the chart below.
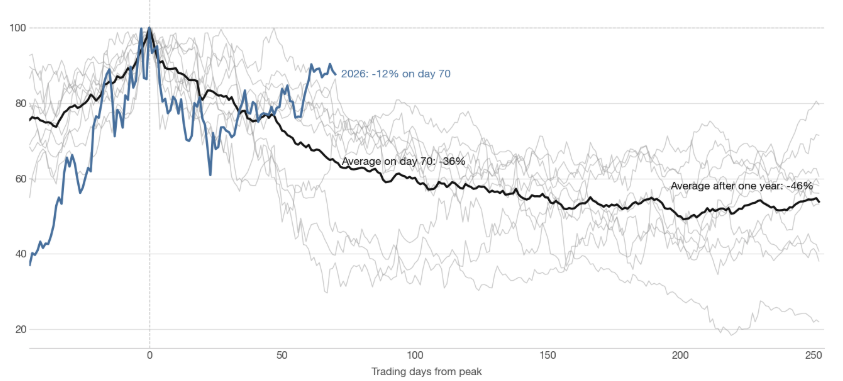
On the DeMark side, I’m seeing a 12 out of 13 countdown on the daily deferral. It’s still very much a sideways range. The biggest risk with shorting, of course, is nothing happens and this continues to drift higher. Is the risk-reward justified from here? I don’t think it’s as good as it was during the peak this summer into the AI craze, especially when we did that update on all the micron leveraged ETFs that were starting to get pushed out there. We’re not seeing anywhere near that level of leverage anymore. And right now, there really has to be a strong catalyst for these things to come down. I do like hedges here, especially into new all-time highs, with these starting to lag relative to the market.